

Getting your mortgage documents together before you apply isn’t just paperwork — it’s the move that separates buyers who close in 30 days from those who scramble for 60. Whether you’re eyeing a craftsman near Blackwater Creek Trail or a colonial close to Peaks View Park, Lynchburg lenders will ask for the same core document package. The difference is how smoothly you deliver it.
This guide covers the tools and resources that make document gathering faster, more organized, and less stressful — starting with a pre-approval process that won’t ding your credit score before you’re even sure which house you want. If you’re comparing lenders right now, bookmark our guide on how to shop for mortgage lenders alongside this one — the two work together.
Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
The Complete Mortgage Document Reference Table
Before diving into the tools, here’s a quick reference for what underwriters actually need and where each document comes from. Every item in this table maps to one or more tools covered below.
| Document Category | What You Need | Where to Get It | Why It Matters to Underwriters |
|---|---|---|---|
| Income – W-2 Employment | W-2s (2 years), pay stubs (30 days most recent) | Employer, IRS Get Transcript | Establishes stable, verifiable income for qualifying ratios |
| Income – Self-Employed | Tax returns (2 years), 1099s, profit/loss statement | IRS Get Transcript, your accountant | Documents net qualifying income after business deductions |
| Income – SSA/Disability | SSA Benefit Verification Letter, award letter | SSA My Account (ssa.gov) | Confirms non-taxable income type and continuance |
| Assets | Bank statements (60 days, all pages), investment/retirement accounts | Your financial institution, YNAB export | Verifies down payment source and cash reserves |
| Credit | Credit report review (borrower-initiated) | AnnualCreditReport.com | Catch errors before lender pulls hard inquiry |
| Identity | Government-issued photo ID, Social Security number | DMV, SSA | Required for identity verification and fraud prevention |
| VA-Specific | Certificate of Eligibility (COE), DD-214, VA disability rating letter | VA.gov, National Archives | Confirms entitlement and funding fee exemption status |
| Property | Purchase agreement, homeowner’s insurance quote | Your real estate agent, insurance provider | Establishes collateral details and coverage requirements |
1. Lynchburg Mortgage Broker – NoTouch Credit Pre-Approval
Best for: Lynchburg buyers who want a personalized document checklist and credit assessment without a hard inquiry.
Lynchburg Mortgage Broker is an independent brokerage run by Duane Buziak, NMLS #1110647, offering a soft-pull VantageScore 4.0 pre-approval that produces a personalized document checklist tied to your specific loan type.
Where This Tool Shines
Most retail lenders — including single-shelf institutions like Atlantic Union Bank, CrossCountry Mortgage, and Freedom First Credit Union — require a hard credit inquiry before they’ll tell you what documents to gather. That means your credit report takes a hit before you’ve even decided on a lender. Duane’s NoTouch Credit process flips that sequence: the soft pull comes first, giving you a credit assessment and a loan-type-specific document checklist without any impact on your score.
The structural advantage here goes beyond credit protection. Because Duane shops hundreds of wholesale lenders rather than working from a single institution’s guideline set, your document package gets evaluated against multiple underwriting programs. If your income documentation is non-standard — self-employed, multiple income streams, VA disability — a broker can often find a program whose guidelines fit your file where one bank’s one rate sheet cannot.
Key Features
NoTouch Credit: Soft-pull VantageScore 4.0 pre-approval with no hard inquiry — your credit score is not affected during the initial assessment.
Personalized Document Checklist: Checklist is tailored to your specific loan type (FHA, VA, conventional, renovation) rather than a generic list that may not apply to your situation.
Dare to Compare: Bring any retail lender quote to Duane and see the wholesale alternative — a direct structural comparison, not a vague promise.
Multi-Lender Evaluation: One application, one document package, evaluated against hundreds of wholesale lender programs simultaneously.
Local Lynchburg Expertise: Active realtor relationships across Central Virginia mean Duane understands the local market, typical purchase timelines, and what Lynchburg sellers expect from a pre-approval letter.
Best For
Any Lynchburg home buyer at the start of their process — especially first-time buyers who aren’t sure what documents they need, veterans pursuing a VA loan, and self-employed borrowers whose income documentation doesn’t fit a standard W-2 mold. If you’re currently holding a quote from a retail lender, the Dare to Compare program is specifically designed for your situation.
Pricing
Free pre-approval consultation. Call (434) 443-7028 or visit lynchburgmortgagebroker.com. NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205.
2. IRS Get Transcript
Best for: Pulling official tax records lenders require — before they ask for them.
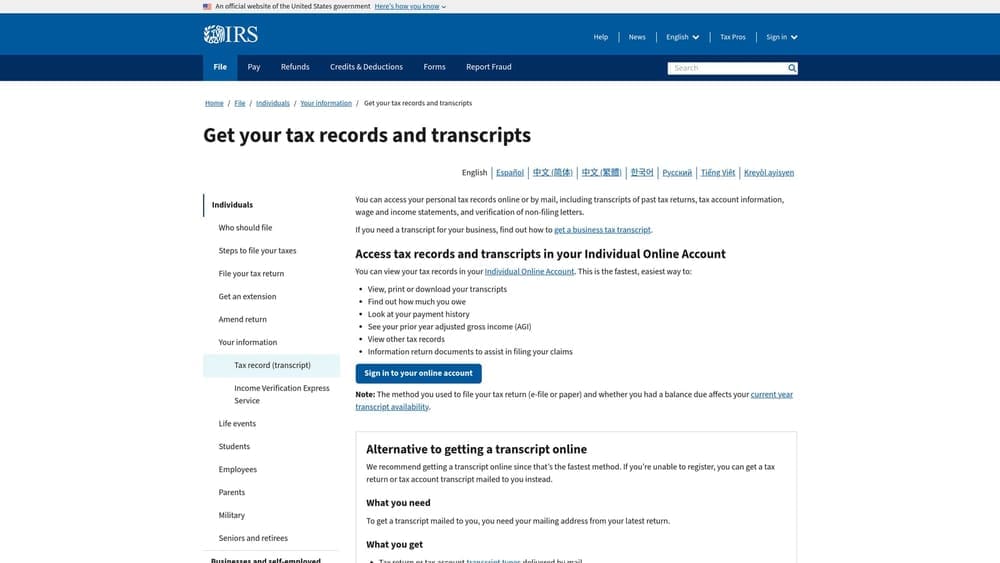
IRS Get Transcript is the federal government’s free online tool for accessing your official tax records — the same records lenders request via Form 4506-C during underwriting.
Where This Tool Shines
Here’s a timing issue most buyers don’t anticipate: lenders don’t just accept the tax returns you hand them. They verify those returns against IRS records using Form 4506-C. If there’s any discrepancy between what you filed and what your lender pulls, it creates a delay — sometimes a significant one. Pulling your own transcripts first lets you spot those discrepancies and address them proactively.
For self-employed borrowers, this is especially important. Two years of tax returns are standard, and the IRS transcript is the authoritative version. Having it ready before your first lender conversation puts you in control of the timeline rather than waiting on IRS processing during underwriting.
Key Features
Tax Return Transcript: Line-by-line income data from filed returns — two years is the standard requirement for most loan programs.
Wage and Income Transcript: Pulls W-2, 1099, and other income source data directly from IRS records for independent verification.
Account Transcript: Confirms filing status and flags any IRS issues a lender might question during underwriting review.
Instant Online Access: Online transcripts are available immediately and accepted by most lenders; mail delivery is also available if needed.
No Cost: Accessing your own IRS records is completely free.
Best For
Every mortgage applicant, but especially self-employed borrowers, contractors, and anyone with multiple income sources. W-2 employees benefit too — having transcripts in hand before your lender requests them can shave days off your processing timeline.
Pricing
Free. No account required for basic transcript access; Identity Verification may be required for online access depending on your IRS account status.
3. SSA My Account – Benefit Verification Letter
Best for: Retirees, disability income borrowers, and surviving spouses documenting SSA income for mortgage qualification.
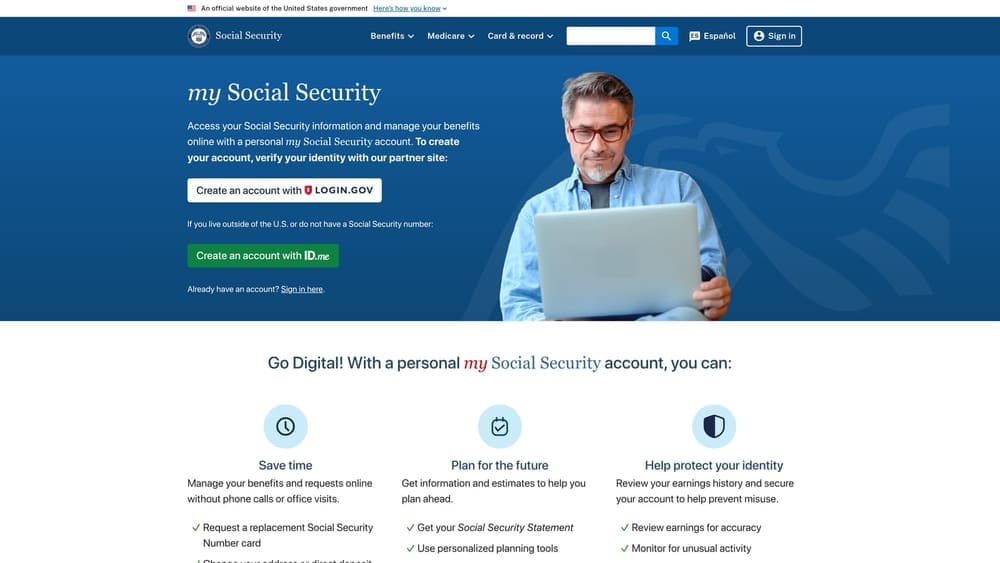
SSA My Account is the Social Security Administration’s online portal for generating an official Benefit Verification Letter — a required document for any borrower whose qualifying income includes Social Security, SSI, or disability payments.
Where This Tool Shines
SSA income is non-taxable for many borrowers, which means it’s often grossed up during underwriting — a calculation that can meaningfully increase your qualifying income. But underwriters need the official documentation to apply that calculation. The Benefit Verification Letter from SSA My Account is the document they accept, and generating it takes about ten minutes online without a trip to a Social Security office.
For VA loan borrowers in Lynchburg who also receive VA disability compensation, this portal works alongside VA.gov (covered in Tool #8) to build a complete income documentation picture. SSA handles Social Security and SSI; VA.gov handles the disability rating letter for VA compensation.
Key Features
Official Benefit Verification Letter: Accepted by FHA, VA, and conventional underwriters as documentation of SSA income type, amount, and payment frequency.
Current Benefit Details: Documents the current benefit amount, payment schedule, and benefit type in a lender-ready format.
24/7 Online Access: No office visit required — generate and download the letter anytime from any device.
VA Disability Complement: Useful alongside VA.gov documentation for borrowers receiving both SSA and VA disability income.
Free Account Setup: Creating an SSA account takes approximately 10 minutes; the letter generates immediately after login.
Best For
Retirees using Social Security as qualifying income, borrowers receiving SSI or disability payments, and surviving spouses with SSA survivor benefits. Also relevant for any co-borrower on a loan application whose income includes SSA payments.
Pricing
Free. A free SSA online account is required to access the portal and generate letters.
4. AnnualCreditReport.com
Best for: Reviewing your credit file for errors before any lender pulls a hard inquiry.
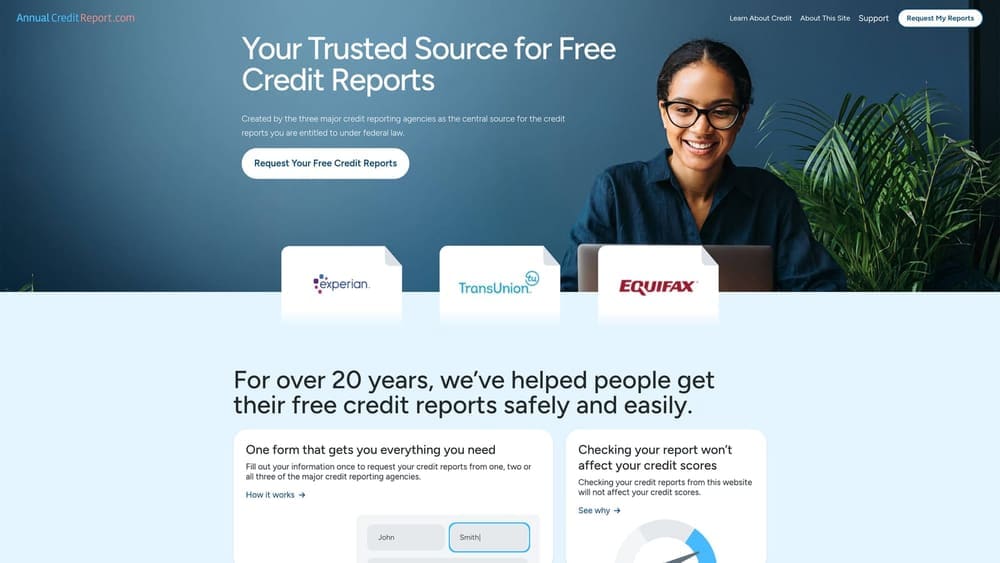
AnnualCreditReport.com is the only federally authorized source for free credit reports from all three major bureaus — Equifax, Experian, and TransUnion — with no impact on your credit score.
Where This Tool Shines
Think of this as your pre-flight check before any lender sees your file. Errors on credit reports are more common than most borrowers expect — duplicate accounts, outdated negative items, or tradelines that don’t belong to you can all affect your rate or approval. Catching and disputing those errors before underwriting begins is far easier than trying to resolve them mid-application.
This tool pairs directly with Duane’s NoTouch Credit process. Review your own report here first, dispute anything inaccurate, and then proceed with a soft-pull pre-approval that doesn’t add a hard inquiry to the file you just cleaned up. That sequence protects your score at every step.
Key Features
Free Weekly Access: All three bureau reports are available weekly at no cost — no credit score impact from checking your own file.
FCRA Authorization: Authorized under the Fair Credit Reporting Act; this is the only site federally mandated to provide free reports from all three bureaus.
Error Identification: Spot reporting errors, duplicate accounts, or fraudulent tradelines before a lender sees your file.
Dispute Access: Initiate disputes directly through each bureau from within the report view — no separate navigation required.
No Account Required: Reports are accessible without creating a permanent account, though saving your report requires downloading it.
Best For
Every mortgage applicant, without exception. Reviewing your credit report before any lender interaction is a foundational step regardless of your loan type, credit history, or how confident you are in your score.
Pricing
Free. Federally mandated under the Fair Credit Reporting Act — no paid tier required for full bureau access.
5. Adobe Acrobat / Adobe Scan
Best for: Converting physical documents into lender-ready PDFs from your phone or desktop.
Adobe Acrobat and the companion Adobe Scan mobile app are the industry standard for turning physical documents — pay stubs, signed forms, bank statements — into the PDF format that underwriters and loan processors work in exclusively.
Where This Tool Shines
Loan processors do not work with photos. A JPEG of your pay stub taken on your phone is not a document — it’s a liability for the person trying to process your file. PDF is the standard, and Adobe Scan converts phone camera photos into clean, flat PDFs that meet lender document requirements. The free mobile app handles this without any desktop software needed.
For buyers assembling a multi-document package, Acrobat’s merge function lets you combine individual PDFs into a single organized file — one document, clearly labeled, rather than a dozen separate attachments. That small organizational step can meaningfully speed up the processor’s review of your file.
Key Features
Adobe Scan (Mobile, Free): Converts phone camera photos into clean, flat PDFs — the format lenders and processors require for all submitted documents.
OCR Technology: Optical character recognition makes scanned documents text-searchable, which helps processors locate specific information quickly.
Document Merging: Combine multiple individual PDFs into a single organized package — useful for submitting a complete bank statement set or tax return package.
Password Protection: Secure sensitive financial documents during transfer to protect personal information.
Acrobat Reader (Free): Handles viewing and basic annotation; Acrobat Standard and Pro add editing and advanced organization features for borrowers with complex document packages.
Best For
Any buyer who has physical documents that need to become digital — which is nearly everyone. Particularly useful for borrowers with older tax returns in paper form, signed gift letters, or any document that originated as a physical paper rather than a digital download.
Pricing
Adobe Scan: Free. Acrobat Reader: Free. Acrobat Standard: approximately $12.99/month. Acrobat Pro: approximately $19.99/month. Most buyers need only the free tiers.
6. Google Drive / Microsoft OneDrive
Best for: Building a centralized, shareable mortgage document folder your loan officer can access directly.
Google Drive and Microsoft OneDrive are cloud storage platforms that function as a central repository for your entire mortgage application package — eliminating email attachment chains and version confusion.
Where This Tool Shines
Here’s a scenario that slows down more applications than any single missing document: a buyer emails a bank statement, then emails an updated version three days later, and the loan processor is working from the wrong one. A shared Drive or OneDrive folder with clearly named subfolders eliminates that problem entirely. Your loan officer accesses the folder directly, always sees the most current version, and can flag what’s missing without a back-and-forth email chain.
The folder structure matters as much as the storage. Organize by category: Income, Assets, Identity, VA Documents (if applicable), Property. Label files clearly — “Bank_Statement_Chase_June2026.pdf” is far more useful than “scan001.pdf” when a processor is reviewing your file at 4pm on a Friday before closing.
Key Features
Dedicated Mortgage Folder: Create a single shared folder with subfolders by document category — keeps your package organized from day one.
Direct Sharing: Share access with your loan officer or broker without emailing large files or managing attachment size limits.
Version History: Both platforms maintain version history, preventing accidentally overwriting an updated statement with an older one.
Any-Device Access: Critical when your lender needs a document same-day and you’re not at your desktop — access and share from your phone in minutes.
Storage Tiers: Google Drive provides 15GB free; OneDrive provides 5GB free with paid tiers starting around $1.99/month for 100GB — more than sufficient for a complete mortgage document package.
Best For
Every buyer, but especially those working with multiple parties — a co-borrower, a real estate agent, and a loan officer all needing access to the same documents simultaneously. Also ideal for buyers who anticipate updating documents (refreshed bank statements, updated pay stubs) during a longer application process.
Pricing
Google Drive: 15GB free. OneDrive: 5GB free. Paid tiers start at approximately $1.99/month. A complete mortgage document package rarely exceeds 500MB — free tiers are sufficient for most buyers.
7. DocuSign
Best for: Signing initial disclosures, loan estimates, and authorization forms electronically without printing or scanning.
DocuSign is the leading e-signature platform used by the majority of lenders and title companies to collect legally binding signatures on mortgage application documents.
Where This Tool Shines
Print-sign-scan is a workflow from 2005. Every hour a signed disclosure sits in a printer tray waiting to be scanned is an hour your application isn’t moving. DocuSign eliminates that entirely — sign from your phone in two minutes, and the signed document is immediately in your lender’s system with a full audit trail.
The compliance piece matters here too. Lenders require timestamped, auditable signatures for initial disclosures and authorization forms. DocuSign’s audit trail satisfies those requirements automatically, which means your loan officer doesn’t have to chase down a compliant signature format.
Key Features
Legally Binding E-Signatures: Compliant with the ESIGN Act and UETA — the same legal standing as a wet signature for mortgage documents.
Audit Trail: Timestamp and activity documentation satisfies lender compliance requirements without any additional steps from the borrower.
Any-Device Signing: Sign from a phone, tablet, or desktop — no printing, scanning, or faxing required at any point in the process.
Co-Borrower Reminders: Automatic reminders for co-borrower signatures prevent the common delay of a second signer forgetting to complete their portion.
No Account Required to Sign: Most lenders send DocuSign envelopes directly to your email — you can sign without creating an account, which removes any setup friction.
Best For
All borrowers — this is a passive tool in the sense that your lender will likely send you DocuSign envelopes regardless of whether you seek it out. Understanding how it works before your first envelope arrives means no delays when initial disclosures need to be returned within the federally required three-business-day window.
Pricing
Free to sign documents sent to you — no account or subscription required for the borrower role. Personal sending plans start around $15/month, but most lenders handle all sending on your behalf.
8. VA.gov – Certificate of Eligibility and Military Documentation
Best for: Lynchburg veterans and active-duty service members gathering VA loan documentation before application.
VA.gov is the authoritative government source for the Certificate of Eligibility (COE), DD-214 requests, and VA disability rating documentation — all required for VA loan underwriting in Virginia.
Where This Tool Shines
The Certificate of Eligibility is the foundational document for any VA loan — without it, underwriting cannot confirm entitlement or determine the correct funding fee (or exemption from it, for veterans with service-connected disability ratings). Many buyers assume their lender will pull the COE automatically. While lenders can often access it through the VA’s automated system, having it in hand before your first conversation removes a variable from the timeline.
For Lynchburg veterans, the VA Regional Loan Center serving Virginia is located in Roanoke — relevant context if COE processing questions arise. The VA Regional Loan Center contact information is available directly through VA.gov for escalation questions.
Key Features
Certificate of Eligibility (COE): Often issued automatically through the VA portal within minutes — the primary entitlement document required for VA loan underwriting.
DD-214 Request: Veterans who don’t have their DD-214 on file can initiate a request through the National Archives via VA.gov — allow additional processing time if this applies to you.
VA Disability Rating Letter: Documents service-connected disability rating for borrowers using VA disability compensation as qualifying income, and confirms funding fee exemption status.
Surviving Spouse Eligibility: Portal includes verification pathways for surviving spouses eligible for VA loan benefits.
Virginia RLC Reference: The Roanoke Regional Loan Center serves Virginia — relevant for COE processing timeline questions specific to this state.
Best For
Any veteran, active-duty service member, or eligible surviving spouse in the Lynchburg area pursuing a VA loan. Start here before any lender conversation — having your COE and DD-214 ready is the single fastest way to accelerate VA loan underwriting.
Pricing
Free. VA.gov is a federal government resource with no cost to access any documentation or eligibility verification services.
9. YNAB (You Need A Budget)
Best for: Organizing 60-day asset history, documenting large deposits, and preparing clean account summaries for down payment sourcing.
YNAB is a personal finance platform that aggregates bank and investment accounts into a single dashboard — useful for documenting the asset history underwriters scrutinize during down payment verification.
Where This Tool Shines
Underwriters don’t just want to see that you have the money for a down payment — they want to know where it came from. Large deposits in the 60 days before your application trigger what’s called “source of funds” documentation requirements. YNAB’s transaction history view lets you identify those deposits proactively, so you’re not scrambling to explain a $5,000 transfer the week before closing.
For self-employed borrowers with income flowing across multiple business and personal accounts, YNAB’s aggregated view is particularly useful. Rather than exporting statements from four different financial institutions and trying to reconcile them manually, you can see the full picture in one place and identify what needs documentation before your loan officer asks.
Key Features
Multi-Account Dashboard: Connects checking, savings, and investment accounts into a single view for comprehensive asset documentation.
Transaction History Export: Identify and document large deposits before underwriting begins — proactive sourcing documentation rather than reactive explanation.
Self-Employed Income Tracking: Particularly useful for borrowers with irregular income across multiple accounts who need to build a coherent income picture.
Gift Fund Documentation: Clearly shows inflow dates and amounts, supporting gift letter documentation requirements for FHA and conventional loans.
Free Trial: 34-day free trial available — sufficient time to document the 60-day asset window most lenders require.
Best For
Self-employed borrowers, buyers using gift funds, and anyone who has moved money between accounts in the 60 days before applying. Also useful for first-time buyers who want a clear view of their total asset position before their first lender conversation.
Pricing
Approximately $14.99/month or approximately $109/year after the 34-day free trial. The free trial alone covers the asset documentation window most lenders require.
A Real-World Document Prep Example: Lynchburg VA Loan Purchase
Let’s walk through exactly what document preparation looks like for a Lynchburg veteran purchasing a $320,000 home with a VA loan — using the tools above in sequence.
Day 1 (approximately 90 minutes): Log into VA.gov and request the Certificate of Eligibility — in most cases, the COE is issued automatically within minutes. If the DD-214 isn’t already on file, initiate that request through the National Archives portal linked from VA.gov. Pull two years of tax transcripts from IRS Get Transcript — the online version is available immediately and takes about 20 minutes including identity verification. Download 60 days of bank statements from your financial institution as PDFs. Organize everything into a Google Drive folder with subfolders labeled Income, Assets, VA Documents, and Identity.
Day 2 (approximately 60 minutes): Review your credit report at AnnualCreditReport.com — all three bureaus, no hard inquiry. Dispute any errors you find directly through each bureau’s portal. Then contact Duane Buziak at (434) 443-7028 for a NoTouch Credit soft-pull pre-approval. The VantageScore 4.0 assessment produces a personalized document checklist specific to your VA loan — confirming what you have and flagging anything still needed. No hard inquiry is generated.
Total document prep time: under three hours across two days.
Now compare that to walking into Atlantic Union Bank or CrossCountry Mortgage without documents prepared. A retail lender working from a single underwriting guideline set will send document request lists piecemeal as each stage of processing reveals the next requirement. Typical delay: five to ten business days of back-and-forth before the file is complete enough to move to underwriting.
The math on a $320,000 purchase: if rate lock timing shifts by two weeks because of document delays, and rates move even modestly in that window, the cost difference on a 30-year loan can be meaningful. Front-loading document prep isn’t just organizational — it’s financial.
Frequently Asked Questions: Mortgage Documents in Lynchburg
What income documents do I need for a mortgage application in Lynchburg? Standard income documentation includes W-2s for the past two years, your most recent 30 days of pay stubs, and two years of federal tax returns. Self-employed borrowers also need 1099s and a year-to-date profit and loss statement. Your loan type may affect the specific requirements — a VA loan and an FHA loan have slightly different income documentation guidelines, which is one reason a personalized document checklist from your loan officer is more reliable than a generic list.
How many months of bank statements does a mortgage lender require? Most lenders require 60 days of bank statements — all pages, including any blank pages. The “all pages” requirement is important: a statement that shows page 1 of 3 but only includes pages 1 and 3 will be flagged and sent back. Download complete statements directly from your online banking portal in PDF format.
Do I need tax returns if I’m a W-2 employee? Yes, in most cases. Two years of federal tax returns are standard for conventional, FHA, and VA loans regardless of employment type. The exception is some conventional loan programs that allow a W-2-only option for straightforward employment situations — ask your loan officer whether your specific scenario qualifies for that streamlined documentation path.
What VA-specific documents do veterans need for a VA loan in Lynchburg? Veterans need a Certificate of Eligibility (COE), a DD-214 (Certificate of Release or Discharge from Active Duty), and — if applicable — a VA disability rating letter documenting service-connected disability income and funding fee exemption status. All three are accessible through VA.gov. The VA Regional Loan Center serving Virginia is in Roanoke.
Will gathering my documents trigger a credit inquiry? No. Pulling your own credit report from AnnualCreditReport.com, using YNAB to review your accounts, downloading IRS transcripts, or generating an SSA Benefit Verification Letter does not trigger any credit inquiry. A hard inquiry only occurs when a lender pulls your credit as part of a formal application. Duane Buziak’s NoTouch Credit pre-approval uses a soft-pull VantageScore 4.0 assessment — no hard inquiry is generated during that process.
What’s the difference between a soft pull and a hard pull during mortgage pre-approval? A soft pull accesses your credit information without creating a record visible to other lenders and without affecting your credit score. A hard pull — the type most retail lenders require before issuing a pre-approval — creates an inquiry on your report that is visible to other lenders and can lower your score by a few points. Multiple hard inquiries within a short window are typically treated as a single inquiry for mortgage rate shopping purposes under FICO scoring, but the inquiry record remains. A soft-pull pre-approval like Duane’s NoTouch Credit process avoids this entirely.
Can I use digital or scanned copies of documents, or do lenders need originals? Digital and scanned copies are accepted by virtually all lenders for the document submission phase of the application. The key requirement is PDF format — not photos. Adobe Scan converts phone camera photos into lender-acceptable PDFs. Some documents (such as a signed gift letter) may need to be wet-signed before scanning; your loan officer will specify when an original signature is required versus when a scanned copy is sufficient.
How far in advance should I start gathering mortgage documents before applying? Start at least 30 days before you intend to submit a formal application — 60 days is better if you’re self-employed or have any complexity in your income or asset picture. This timeline gives you space to pull IRS transcripts, review and dispute credit report errors, gather complete bank statements for the required 60-day window, and address any documentation gaps before they become underwriting delays. Starting early also means you’re not rushing to gather documents while simultaneously negotiating a purchase contract.
Which Tools Are Right for Your Situation
If you’re a first-time buyer in Lynchburg, start with the NoTouch Credit pre-approval at Lynchburg Mortgage Broker. You’ll get a lender-guided document checklist and a soft-pull credit assessment that won’t affect your score while you’re still exploring your options. That checklist is more useful than any generic list because it’s specific to your loan type and financial profile.
Veterans should add VA.gov to that starting point immediately — pull your COE and DD-214 before any other step. Those documents have the longest potential lead time in the entire package, and having them ready before your first lender conversation removes the most common VA loan delay from the equation.
Self-employed borrowers should prioritize IRS Get Transcript and a clean PDF organization system in Google Drive or OneDrive. Two years of tax transcripts, organized and verified before your lender requests them, puts you in control of the underwriting timeline rather than waiting on IRS processing mid-application.
Everyone benefits from reviewing AnnualCreditReport.com before any lender pulls a hard inquiry. The single biggest mistake Lynchburg buyers make is showing up to a lender — whether that’s Atlantic Union Bank, CrossCountry Mortgage, or Freedom First Credit Union — without a complete document package. A retail lender with one rate sheet has limited flexibility if your file has a wrinkle. An independent broker shopping hundreds of wholesale lenders can often find a program that fits your specific income documentation, credit profile, and loan type.
Ready to get your document package in front of multiple lenders at once? Schedule your free consultation today with Duane Buziak at (434) 443-7028 — soft-pull pre-approval, no hard inquiry, no obligation. NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205.
Also explore the first-time home buyer resources on LynchburgMortgageBroker.com, and see our breakdown of VantageScore 4.0 mortgage approval to understand exactly how the NoTouch Credit pull works.
About the Author: Duane Buziak, NMLS #1110647, is the owner of LynchburgMortgageBroker.com and a licensed mortgage broker through Coast2Coast Mortgage LLC, NMLS #376205. Licensed in Virginia, Florida, Tennessee, Georgia, and Washington D.C. Duane has been helping families find their new homes since 2014, ranked #114 nationally on the Scotsman Guide, named VA Broker of the Year 2024–2025, and recognized as a UWM PRO ELITE 2025 broker. As an independent broker with access to hundreds of wholesale lenders, Duane shops the market on your behalf — one application, multiple programs, one local expert who knows Lynchburg. Call (434) 443-7028 or visit lynchburgmortgagebroker.com.
