

Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
If you’re shopping for a home near Blackwater Creek Trail or eyeing a property close to Percival’s Island, the last thing you want is a stack of hard credit inquiries dragging your score down before you’ve even made an offer. The good news: soft-pull pre-approval is real, and more lenders are offering it in 2026 — but not all soft-pull options are created equal.
Some give you a genuine wholesale rate comparison across hundreds of lenders. Others hand you a single rate from a single shelf and call it a day. This guide covers the pre-approval options available to Lynchburg-area buyers, what each one actually delivers, and why the structure behind the pre-approval matters just as much as the credit pull method.
We evaluated each option on four criteria: credit pull type, lender access, loan program depth, and local accountability.
Understanding Soft-Pull vs. Hard-Pull Pre-Approval
A soft credit inquiry does not appear on your credit report as a lender inquiry and does not affect your credit score under either FICO or VantageScore models. A hard inquiry typically remains on your credit report for two years and can reduce your score modestly — the exact impact varies by your individual credit profile.
Here’s the nuance most buyers miss: multiple mortgage hard inquiries within a short window (typically 14 to 45 days, depending on the scoring model) are often treated as a single inquiry for rate-shopping purposes. However, the initial inquiry still registers. If you’re already carrying a borderline score or plan to apply for other credit soon, even one unnecessary hard pull can matter.
VantageScore 4.0 is the newer scoring model that enables genuine soft-pull pre-approvals. Most retail banks and lenders still default to a FICO 2/4/5 tri-merge hard pull at pre-approval. That distinction is the structural difference that separates the first option below from every other option on this list.
1. Lynchburg Mortgage Broker — Duane Buziak / Coast2Coast Mortgage
Best for: Credit-sensitive buyers who want a real rate shopped across hundreds of wholesale lenders with zero score impact.
Lynchburg Mortgage Broker is the only option on this list that combines a genuine soft-pull pre-approval with wholesale broker access to hundreds of lenders — meaning the rate behind the pre-approval is actually shopped, not pulled from a single institution’s rate sheet.
Where This Option Shines
The core differentiator here is structural. Duane Buziak operates as an independent broker, which means he is not employed by any one lender and is not limited to any one rate sheet. When you submit for a NoTouch Credit pre-approval, your profile is assessed using VantageScore 4.0 — a soft pull that leaves your score completely untouched — and then positioned across hundreds of wholesale lenders to find the sharpest available rate for your profile.
This matters most when you’re still in the shopping phase. You can get a real pre-approval letter, understand your actual buying power, and take that number to a seller — all without a single hard inquiry on your report. For buyers near Peaks View Park or anywhere in the Lynchburg MSA working with one of Duane’s active realtor partners, this pre-approval carries weight in a competitive offer situation.
Key Features
NoTouch Credit: VantageScore 4.0 soft pull at pre-approval — zero impact to your credit score, no hard inquiry required to see your real options.
Wholesale Broker Model: Pre-approval is backed by access to hundreds of wholesale lenders, not one institution’s rate sheet — the rate you see is a shopped rate.
Dare to Compare: Bring any existing quote from another lender and receive a side-by-side wholesale alternative at no cost or obligation.
Full Program Depth: FHA, VA, USDA, Conventional, Jumbo, Renovation, and First-Time Buyer programs all available through one broker relationship — no referrals to different departments.
Local Lynchburg Presence: Active realtor referral network already in-market, with direct phone access at (434) 443-7028.
Best For
First-time buyers, credit-rebuilding buyers, rate shoppers who don’t want multiple hard pulls before committing, and any buyer who already has a quote from another lender and wants to verify whether they’re getting the market rate. Also ideal for veterans using VA loan benefits who want to maximize their purchasing power through wholesale pricing.
Pricing
No cost for pre-approval. Broker compensation is disclosed at application per RESPA requirements. Call (434) 443-7028 to start your NoTouch Credit pre-approval.
2. Atlantic Union Bank — Jay Brown
Best for: Existing Atlantic Union customers and medical professionals seeking physician loan products in Central Virginia.
Atlantic Union Bank is a well-established Virginia regional bank with a 30-plus year local origination track record, specializing in physician loans and new construction financing in the Lynchburg market.
Where This Option Shines
Jay Brown’s longevity in the Lynchburg market is a genuine credential. Thirty-plus years of local origination means established relationships with builders, real estate attorneys, and appraisers in Central Virginia — and that institutional familiarity can smooth the process for buyers purchasing new construction or working on construction-to-perm financing.
For existing Atlantic Union banking customers, there may be relationship pricing advantages worth exploring. The physician loan specialty is also a real differentiator for medical professionals at Centra Health or the hospital corridor who need flexible debt-to-income treatment for student loan obligations.
Key Features
30-Plus Year Local Track Record: Deep Lynchburg and Central Virginia origination history with established builder and referral relationships.
Physician Loan Specialty: Medical professional loan products designed for high-income borrowers with significant student loan debt.
New Construction Focus: Construction and construction-to-permanent loan products with local builder familiarity.
Existing Customer Relationship: Potential banking relationship benefits for current Atlantic Union account holders.
Best For
Medical professionals, buyers purchasing new construction in the Lynchburg area, and existing Atlantic Union Bank customers who value a consolidated banking relationship. Less suited for buyers who want to compare rates across multiple lenders or who need a soft-pull pre-approval.
Pricing
Standard bank rate sheet pricing. No documented soft-pull pre-approval option is available through the standard retail channel — pre-approval typically involves a hard credit pull using tri-merge FICO scores. Buyers who want to compare Atlantic Union’s rate against a wholesale alternative can use the Dare to Compare program at LynchburgMortgageBroker.com.
3. CrossCountry Mortgage — April DeShano
Best for: First-time homebuyers seeking guided educational support from a local originator backed by national retail infrastructure.
CrossCountry Mortgage is a national retail mortgage lender with a local Lynchburg-area originator known for guiding first-time homebuyers and refinance clients through the loan process.
Where This Option Shines
April DeShano’s local reputation centers on education and hand-holding for buyers who are new to the mortgage process. For a first-time buyer who feels overwhelmed by the paperwork and terminology, having a local originator who prioritizes explaining each step has real value. CrossCountry’s national infrastructure also means solid processing and underwriting systems behind the scenes.
CrossCountry does offer a national-level soft-pull initial screening tool called Cross-Qualify at the brand level. It’s worth noting, however, that this functions as a marketing and lead-qualification tool — it is not a full broker-backed soft-pull pre-approval with wholesale lender access. The rate you receive is CrossCountry’s rate, drawn from CrossCountry’s own pricing engine.
Key Features
First-Time Buyer Guidance: Educational focus and step-by-step support for buyers navigating the mortgage process for the first time.
Refinancing Specialization: Local expertise in refinance transactions for existing Lynchburg homeowners.
National Retail Infrastructure: CrossCountry’s processing and underwriting systems support consistent loan delivery timelines.
Standard Program Suite: Conforming, FHA, and VA loan products available through CrossCountry’s retail channel.
Best For
First-time buyers who prioritize education and local guidance over rate shopping, and existing homeowners exploring refinancing options. Buyers who want to compare CrossCountry’s retail rate against a wholesale alternative can bring their quote to the Dare to Compare program.
Pricing
Retail lender pricing drawn from CrossCountry’s own rate sheet. No multi-lender comparison is available — the rate you receive is CrossCountry’s rate for that day. National online application is available.
4. Freedom First Credit Union — Courtney Woody
Best for: Qualifying credit union members who want VA, FHA, or VHDA loan products from a locally recognized institution.
Freedom First Credit Union is a Virginia-based credit union offering mortgage products including VA, FHA, and VHDA loans to members, with a strong local reputation in the Lynchburg market.
Where This Option Shines
Credit unions operate on a member-owned, not-for-profit model, which can sometimes translate to favorable pricing for qualifying members — particularly on deposit-heavy or relationship-based products. Courtney Woody’s Platinum Reader’s Choice recognition reflects genuine local trust, and Freedom First’s construction loan availability adds flexibility for buyers building in the Lynchburg area.
VHDA (Virginia Housing Development Authority) loan access is a meaningful differentiator for first-time buyers who qualify for Virginia’s state-level down payment assistance and below-market rate programs. If you meet VHDA income and purchase price limits, Freedom First’s VHDA product is worth evaluating.
Key Features
VA, FHA, and VHDA Programs: State and government-backed loan products available for qualifying members.
Credit Union Membership Model: Member-owned structure with potentially favorable terms for qualifying Freedom First members.
Local Recognition: Platinum Reader’s Choice winner with established Lynchburg community presence.
Construction Loans: Construction loan products available for buyers building in the Central Virginia area.
Best For
Existing Freedom First members, buyers who qualify for VHDA down payment assistance, and buyers who prefer a local credit union relationship over a national lender. Membership is required — non-members will need to join before accessing mortgage products.
Pricing
Credit union rate sheet pricing — rates are set by Freedom First’s own cost of funds and board-approved rate structure. Membership is required. No wholesale market comparison is available; the rate you receive is Freedom First’s rate for qualifying members.
5. Luper Team Mortgage — Fairway Independent Mortgage Corporation
Best for: Buyers who prioritize high local transaction volume and strong social proof from a well-reviewed local team.
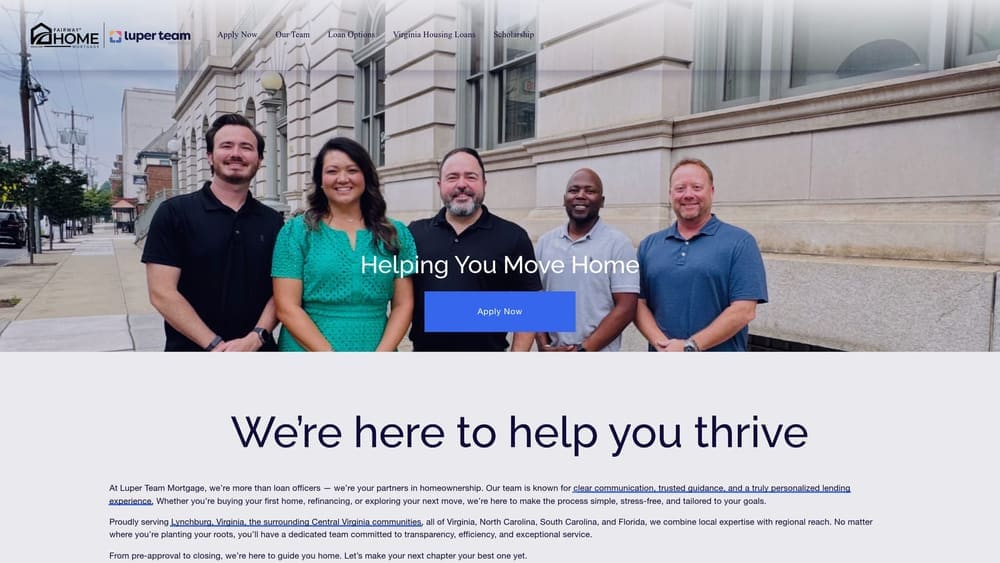
Luper Team Mortgage is a high-volume local mortgage team powered by Fairway Independent Mortgage Corporation, with 900-plus completed transactions and 284-plus Google reviews — one of the strongest local social proof profiles in the Lynchburg market.
Where This Option Shines
Volume and reviews tell you something real: the Luper Team has processed a significant number of Lynchburg-area transactions, which means experience with local appraisal conditions, title companies, and real estate transaction norms specific to Central Virginia. A four-person origination team also means more coverage and faster response times during busy periods.
For buyers who are primarily motivated by finding a lender with a proven local track record and strong peer reviews, the Luper Team’s numbers are hard to argue with. The important structural note is that Fairway Independent Mortgage Corporation is a direct lender, not a broker — the rate you receive is Fairway’s rate for that day, not a rate shopped across multiple wholesale investors.
Key Features
900-Plus Local Transactions: High Lynchburg-area transaction volume with deep local market familiarity.
284-Plus Google Reviews: One of the strongest local social proof profiles among Lynchburg mortgage originators.
Four-Person Team: Multi-originator team with varied loan specializations and broader availability.
Standard Program Suite: Fairway’s conforming, FHA, VA, and USDA loan products available through the retail channel.
Best For
Buyers who place high value on peer reviews and proven local transaction experience, and who are comfortable with a single-lender pricing model. Buyers who want to see how Fairway’s rate compares to a wholesale alternative can bring their Luper Team quote to the Dare to Compare program.
Pricing
Fairway Independent Mortgage retail pricing — single lender rate sheet. No wholesale market comparison is available. The rate you receive reflects Fairway’s pricing for your loan profile on that day.
6. The Loan Maven Team — Rhonda Holt / RWM Home Loans
Best for: Buyers who want a highly experienced originator with 30 years of mortgage history and strong Lynchburg name recognition.
The Loan Maven Team is led by Rhonda Holt, NMLS #217259, a 30-year veteran originator operating as a branch manager under RWM Home Loans (Residential Wholesale Mortgage Inc., NMLS #79445), with 97-plus Google reviews and deep Lynchburg community presence.
Where This Option Shines
Thirty years of origination experience is a meaningful credential. Rhonda Holt has navigated multiple rate cycles, market corrections, and regulatory shifts — and that experience translates to problem-solving capability when a loan file hits an unexpected complication. Her 97-plus Google reviews reflect a long track record of client satisfaction in the Lynchburg market.
One point worth clarifying for buyers: despite the word “Wholesale” appearing in the parent company name (RWM stands for Residential Wholesale Mortgage), Rhonda Holt operates as a retail loan originator. Borrowers receive RWM Home Loans’ rate — not a rate shopped across multiple wholesale investors. This is a common source of confusion and worth understanding before assuming the pricing model matches the company name.
Key Features
30 Years of Origination Experience: Three decades of mortgage experience across multiple market cycles and regulatory environments.
97-Plus Google Reviews: Established local authority with a strong community reputation in Lynchburg.
Branch Manager Access: Branch manager level within RWM Home Loans with full retail program access.
Best For
Buyers who prioritize originator experience and long-term local reputation above all else. Well-suited for complex loan scenarios where an experienced hand matters. Buyers who want to verify whether RWM’s retail rate is competitive against the wholesale market can bring their quote to the Dare to Compare program.
Pricing
RWM Home Loans retail pricing. Note: despite “Wholesale” in the parent company name, borrowers receive one retail lender’s rate — not a rate shopped across the wholesale market. This distinction matters for buyers comparing total loan cost.
A Worked Dollar Example: What the Pricing Structure Difference Can Mean
Here’s a concrete scenario to illustrate why the structure behind a pre-approval matters beyond the credit pull method.
Scenario: $350,000 purchase price, 20% down ($70,000), $280,000 loan amount, 30-year fixed, buyer with a 740 VantageScore 4.0 (approximately 720 to 740 FICO equivalent).
As of mid-2026, published retail 30-year fixed rates for well-qualified borrowers are generally running in a range that wholesale pricing can often undercut by 0.125% to 0.25% depending on the day and the lender. On a $280,000 loan, a 0.25% rate difference translates to approximately $41 per month in payment savings. Over a 30-year loan term, that differential compounds to roughly $14,700 in total interest — before accounting for any refinance activity.
The soft-pull pre-approval doesn’t change this math. What it does is let you arrive at this comparison without a hard inquiry on your report. You see the real number first, then decide whether to proceed — not the other way around.
Note: Rate figures vary daily. For a current side-by-side comparison specific to your loan profile, call (434) 443-7028 or use the Dare to Compare program at LynchburgMortgageBroker.com.
Broker vs. Single-Shelf Lender: A Structural Comparison
| Dimension | Lynchburg Mortgage Broker (Duane Buziak) | Atlantic Union Bank (Jay Brown) | CrossCountry Mortgage (April DeShano) | Freedom First CU (Courtney Woody) | Luper Team / Fairway |
|---|---|---|---|---|---|
| Credit Pull at Pre-Approval | Soft pull — VantageScore 4.0, zero score impact | Hard pull — tri-merge FICO standard | Soft-pull screening tool available; full pre-approval requires hard pull | Hard pull — credit union standard process | Hard pull — Fairway retail standard |
| Lender Access | Hundreds of wholesale lenders — rate is shopped | Atlantic Union Bank only — one rate sheet | CrossCountry Mortgage only — one rate sheet | Freedom First CU only — membership required | Fairway Independent Mortgage only — one rate sheet |
| Loan Program Depth | FHA, VA, USDA, Conventional, Jumbo, Renovation, First-Time Buyer — all in one relationship | Physician loans, new construction, standard conforming | Conforming, FHA, VA — CrossCountry’s product menu | VA, FHA, VHDA, construction — Freedom First’s product menu | Conforming, FHA, VA, USDA — Fairway’s product menu |
| Dare to Compare / Rate Shopping | Yes — bring any quote for a wholesale side-by-side comparison | No — single institution pricing | No — single lender pricing | No — single institution pricing | No — single lender pricing |
Frequently Asked Questions
What is the difference between a soft pull and a hard pull for mortgage pre-approval?
A soft pull accesses your credit information without creating a lender inquiry on your report — it does not affect your credit score. A hard pull is a formal credit inquiry that appears on your report and can modestly reduce your score. Most retail banks and lenders use a hard pull (tri-merge FICO) for pre-approval. Duane Buziak’s NoTouch Credit uses VantageScore 4.0 — a soft pull — so your score is never touched during the pre-approval process.
Will a soft-pull pre-approval letter be accepted by sellers and real estate agents in Lynchburg?
Yes. A pre-approval letter documents that a licensed mortgage professional has reviewed your income, assets, and credit profile and determined you qualify for financing up to a stated amount. The credit pull method used to generate that letter is not visible to sellers or their agents — what matters is the letter itself, the lender’s credibility, and the loan amount. A soft-pull pre-approval from a licensed broker is a fully valid pre-approval letter for offer purposes.
What is VantageScore 4.0 and how does it differ from the FICO score lenders typically use?
VantageScore 4.0 is a credit scoring model developed by the three major credit bureaus as an alternative to FICO. It uses a similar 300 to 850 scale but incorporates trended data and can score consumers with shorter credit histories. Most retail mortgage lenders still use FICO 2, 4, and 5 tri-merge scores for underwriting decisions. VantageScore 4.0 is used here specifically for the soft-pull pre-approval stage — giving buyers an accurate read on their credit profile without triggering a hard inquiry. The CFPB provides a useful overview of how credit scores and scoring models work.
Can I get pre-approved with a 620 credit score without a hard inquiry?
Yes — a soft-pull pre-approval using VantageScore 4.0 does not require a hard inquiry regardless of your score. Whether a 620 score qualifies you for specific loan programs depends on the program guidelines: FHA loans are available to borrowers with scores as low as 580 with a 3.5% down payment under HUD guidelines, while conventional loans typically require higher scores for the best pricing. A soft-pull pre-approval will identify which programs you qualify for at your current score without touching your credit.
How many hard inquiries are too many before applying for a mortgage?
There is no universal threshold, but multiple recent hard inquiries in unrelated credit categories (auto loans, credit cards, personal loans) can signal credit-seeking behavior that lenders view cautiously. For mortgage-specific shopping, FICO and VantageScore both apply a rate-shopping window — typically 14 to 45 days depending on the model — during which multiple mortgage inquiries are treated as a single inquiry. The safest approach is to use a soft-pull pre-approval for initial shopping and reserve any hard pull for the lender you intend to proceed with.
Does shopping multiple lenders hurt my credit score?
Shopping multiple mortgage lenders within the rate-shopping window (14 to 45 days depending on the scoring model) typically results in those inquiries being grouped and counted as one. However, if each lender you contact runs a separate hard pull before you’ve selected a lender, each inquiry still registers initially. The cleanest approach: use a soft-pull pre-approval to identify your real options first, then authorize a hard pull only with the lender you’ve chosen. The CFPB explains the rate-shopping window in detail.
What documents do I need for a soft-pull pre-approval?
A soft-pull pre-approval typically requires your Social Security number (to run the soft pull), two years of W-2s or tax returns, recent pay stubs (30 days), two to three months of bank statements, and documentation of any other assets used for the down payment. Self-employed borrowers will generally need two years of business and personal tax returns. Because no hard inquiry is run, the document list is the same as a standard pre-approval — only the credit pull method differs.
How long does a soft-pull pre-approval letter remain valid?
Pre-approval letters — whether generated from a soft pull or a hard pull — are typically valid for 60 to 90 days, after which income and asset documentation may need to be refreshed. If your home search extends beyond that window, a simple document update is usually all that’s required to reissue the letter. Your credit profile does not need to be re-pulled as a hard inquiry simply because the letter is being refreshed, depending on the lender’s process.
Local Data Context: Lynchburg-Area Home Prices
The Lynchburg MSA has seen sustained demand from buyers relocating within Central Virginia and from outside the region. For current median home price data specific to the Lynchburg and Central Virginia market, refer to the Virginia REALTORS® Market Data page, which publishes monthly and quarterly reports by MSA. At the time of publication, buyers should verify current figures directly from Virginia REALTORS® most recent available report — market conditions in 2026 have continued to reflect limited inventory in desirable Lynchburg neighborhoods.
For buyers targeting properties near Amazement Square, the Blackwater Creek corridor, or the established neighborhoods surrounding Poplar Forest, understanding your pre-approved buying power before entering a competitive offer situation is particularly important. A soft-pull pre-approval lets you establish that number without any credit risk while you’re still in the exploration phase.
Making the Right Choice for Your Lynchburg Home Purchase
For Lynchburg buyers who want to protect their credit score during the pre-approval process, the soft-pull option is the clear starting point — but the structure behind that pre-approval determines whether you’re getting one lender’s best guess or a genuine market rate.
Atlantic Union Bank, CrossCountry Mortgage, Freedom First Credit Union, and the Luper Team are all capable local originators with real track records and genuine strengths for specific buyer profiles. What they share is a single-shelf constraint: each one can only offer what their one lender or institution prices that day. Rhonda Holt at RWM Home Loans brings 30 years of experience to the table, and despite the word “Wholesale” in the parent company name, borrowers receive one retail lender’s rate — not a multi-lender comparison.
Duane Buziak’s NoTouch Credit pre-approval at LynchburgMortgageBroker.com runs on VantageScore 4.0 — a soft pull that leaves your score untouched — and then shops that profile across hundreds of wholesale lenders to find the sharpest rate available for your specific loan profile. If you already have a quote from any lender on this list, the Dare to Compare program exists specifically to show you the wholesale alternative side by side.
No hard pull. No commitment. Just a real number to compare against whatever you’ve already been quoted.
Schedule your free consultation today to start your NoTouch Credit soft-pull pre-approval. Call (434) 443-7028. NMLS #1110647. Pre-approval is soft-pull only — no hard inquiry required to see your real options.
Already have a quote? Bring it. The Dare to Compare program will show you the wholesale alternative at no cost or obligation.
About Duane Buziak
Duane Buziak, NMLS #1110647, is the broker-owner of LynchburgMortgageBroker.com, operating under Coast2Coast Mortgage LLC, NMLS #376205. Helping families find their new homes since 2014, Duane is an independent mortgage broker with access to hundreds of wholesale lenders across conventional, FHA, VA, USDA, Jumbo, and renovation loan programs. Ranked #114 in the Scotsman Guide, VA Broker of the Year 2024 and 2025, and UWM PRO ELITE 2025. Licensed in Virginia, Florida, Tennessee, Georgia, and Washington DC.
Contact: (434) 443-7028 | LynchburgMortgageBroker.com | NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
