

Lynchburg buyers hear “prequalified” and “preapproved” used as if they mean the same thing, then learn at the offer stage that sellers and listing agents weigh them very differently. This list is for buyers deciding where to get a verified approval letter, and it compares five local options on four points: how credit is pulled, what documents are required, how strong the resulting letter is, and whether the lender can look beyond its own rate sheet. Terms change, so confirm each lender’s current policies directly.
Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
Quick Comparison of the Five Lynchburg Options
- Duane Buziak: buyers who want a verified letter without a hard inquiry; pricing quoted per borrower; the only option here that shops hundreds of wholesale lenders instead of one rate sheet.
- Atlantic Union Bank: existing bank customers, new-construction and medical-professional borrowers; pricing quoted per borrower; construction-to-permanent financing tied to a deposit relationship.
- CrossCountry Mortgage: first-time buyers who want an app-driven process; pricing quoted per borrower; a national retail platform with a structured digital document upload.
- Freedom First Credit Union: members and buyers using VHDA or VA programs; pricing quoted per borrower; credit union membership combined with government-backed loan experience.
- Luper Team Mortgage: buyers who want a local branch team with a strong reputation; pricing quoted per borrower; a high-touch local team operating under a national lender’s systems.
1. Duane Buziak
Lynchburg Mortgage Broker by Duane Buziak is an independent brokerage covering purchase, FHA, VA, refinance, renovation and commercial loans. Its pre-approval starts with NoTouch Credit, a soft-pull review that does not create a hard inquiry, followed by document verification that turns the estimate into an approval letter.
The structural difference is in how the rate is found. Duane Buziak submits your file across hundreds of wholesale lenders and picks the program that fits your credit, down payment and timeline. The lenders on the rest of this list quote from one institution’s menu.
- NoTouch Credit soft-pull pre-approval lets you see loan options without a single credit hit while you are still deciding.
- VantageScore 4.0 credit assessment can read thin or recovering files differently than older scoring models, which matters for first-time buyers.
- Access to hundreds of wholesale lenders means a conventional, FHA or VA scenario can be priced against many guidelines at once.
- FHA, VA and first-time buyer programs are handled in-house, so you do not need a separate referral for each.
- A free homebuyer resource center explains the steps before you commit to anything.
On setup, you work directly with Duane Buziak, who coordinates with wholesale lender platforms and the local realtor referral network already active in Lynchburg. Expect to provide the usual verification items: pay stubs, bank statements and tax documents.
The limits are real. A broker does not fund loans itself, so the loan closes with a wholesale lender, and the final rate and underwriting conditions come from that lender. Licensing covers VA, FL, TN, GA and DC only, so it does not suit buyers purchasing elsewhere. A soft-pull letter is also conditional: a full credit report is eventually needed for underwriting on the loan you choose. Pricing is quoted per borrower and moves with credit profile, down payment, loan type and occupancy.
Best for: Buyers who want a verified approval letter without a hard inquiry and want rates compared across lenders.
2. Atlantic Union Bank
Atlantic Union Bank is a regional bank with local mortgage lending. Its appeal is the relationship: your checking, savings and mortgage can sit under one roof, and a local loan officer handles the file.
Its most distinctive offerings on this list are construction-to-permanent financing and programs for physicians and medical professionals. Both are worth verifying as of today, since bank menus change. If you are building rather than buying an existing home, that single-close structure can matter more than a rate difference of a few basis points.
What you get
- A local loan officer who knows the market and can be reached without a call center.
- Possible medical-professional loan terms, which are worth asking about if you qualify.
- Construction-to-permanent lending that avoids closing twice on a new build.
- A deposit account relationship that can simplify document gathering, since your statements are already in the bank.
Where it falls short
Everything you are offered comes from one institution’s rate sheet and guidelines. If your income, credit or property type sits awkwardly against those guidelines, there is no second lender inside the same office to try. Ask directly whether the letter is issued after a hard or soft credit pull, because the policy is not something to assume.
Setup runs through the bank’s loan officer and online banking portal. Pricing is quoted per borrower and moves with credit, down payment, loan type and, in some bank programs, the size of your deposit relationship.
Best for: Existing bank customers and new-construction or medical-professional borrowers.
3. CrossCountry Mortgage
CrossCountry Mortgage is a national retail lender with a local Lynchburg loan officer, known for walking first-time buyers through the process. The experience is built around a digital application and document upload, so much of the work happens from your phone or laptop.
That structure is a real strength for buyers who dislike paperwork in person. You upload income and asset documents, the file is reviewed, and a letter follows. Its national scale also means it has processing infrastructure that a very small shop may not.
- Digital application and upload cut down on emailing scattered PDFs.
- First-time buyer guidance explains each step, such as what an appraisal does and when to lock.
- Conventional, FHA and VA programs are generally offered (verify the current menu).
- Refinance options let you stay with the same lender if you refinance later.
Setup effort is moderate: you complete the online application, then your loan officer and a processing team handle follow-ups. The limitation is the same as any single-lender setup. The approval reflects one company’s products and pricing, so a competing offer from another lender has no way of showing up in your file. Confirm credit-pull timing before you apply, because that determines whether the first step affects your score.
Pricing is quoted per borrower and moves with credit score, loan-to-value, loan type and the points you choose.
Best for: First-time buyers who want a guided, app-driven process.
4. Freedom First Credit Union
Freedom First Credit Union is member-owned, and that shapes everything about it. You join the credit union, and your mortgage sits alongside your checking and savings. Menus change, so verify the current list of VA, FHA, VHDA and construction loans.
The notable feature here is experience with Virginia-specific and government-backed programs. VHDA lending in particular can unlock down payment help for eligible Virginia buyers, and a lender that works with it regularly will know the paperwork. If you are a veteran, review the VA home loan guidelines before you compare any lender’s VA offer, so you know what a Certificate of Eligibility does and does not cover.
Limits to weigh
You need to qualify for membership before applying, which adds a small step. The product menu is also a single institution’s menu, so unusual scenarios such as certain investor purchases or non-standard income may not fit. Your letter will reflect that one menu and its pricing.
- VA and FHA loans for buyers who want government-backed financing.
- VHDA program lending that may be paired with down payment help.
- Construction loans for buyers building a home.
- Credit union membership that may bring lower account fees and local service.
Setup runs through credit union accounts and its loan staff. Pricing is quoted per borrower and depends on credit, down payment, program and membership status.
Best for: Members and buyers using VHDA or VA programs through a local credit union.
5. Luper Team Mortgage
Luper Team Mortgage is a local Lynchburg branch team led by Will and Joanna Luper, operating under Fairway Independent Mortgage Corporation. Verify current branch details before you rely on that arrangement.
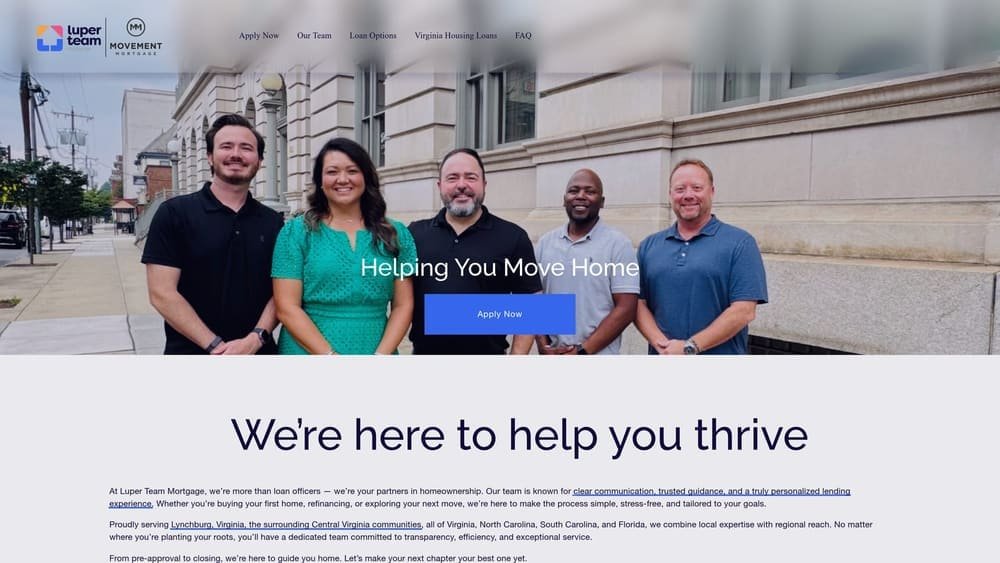
The draw is a high-touch, team-based process. Instead of one loan officer juggling every task, a small local team covers the steps, and the group is known for local reviews. If you cite a review count, check which platform it comes from and the date, because those numbers move.
The trade-off is on the pricing side. Because the branch operates under one funding lender, rates come from that company’s rate sheet, so you are comparing one local team’s service against a single set of products. Confirm credit-pull timing before authorizing anything, since that decides whether you get a letter without a hard inquiry.
- A local team process means questions get answered by people who know Lynchburg neighborhoods.
- Purchase and refinance loans cover the common cases.
- A branch of a national lender gives it established systems for underwriting and closing.
- Strong local review presence can give you a way to check experiences against your own expectations.
Setup runs through Fairway’s lender systems, with the local team coordinating. Pricing is quoted per borrower and moves with credit score, down payment, loan type and lock period.
Best for: Buyers who prioritize a local branch team and strong local reputation.
Prequalification and Approval Letters: What Each One Proves
A prequalification is an estimate built from numbers you report yourself, often within minutes. It is not a commitment to lend, and nobody has checked your pay stubs or bank statements. A pre-approval, or approval letter, comes after a lender reviews verified documents and your credit, and it is still conditional on the appraisal, title and final underwriting. That verified review is why listing agents give it more weight.
On credit, a soft pull checks your file without leaving a hard inquiry, while a hard pull is recorded on your report. The CFPB’s home buying resources explain that mortgage inquiries made while rate shopping within a short window are generally treated as a single inquiry for scoring, but confirm how your own score model handles it. Also check the loan size against the current conforming limit: FHFA’s 2026 announcement sets the baseline at $832,750 as of this writing. For FHA scenarios, see HUD’s loan overview.
Locally, U.S. Census QuickFacts reports Lynchburg’s 2020 census population at 79,009, a mid-sized market where realtors know which letters carry weight.
A Worked Example of Why Rate Sourcing Matters
The following uses hypothetical rates for illustration only and is not a quote. Suppose you buy a $350,000 home in Lynchburg with 5% down. The down payment is $17,500 and the loan is $332,500 on a 30-year fixed term.
- At a hypothetical 6.50% from a single rate sheet, principal and interest is about $2,101.63 a month.
- At a hypothetical 6.25% from a wholesale lender found by shopping, it is about $2,047.27 a month.
- The difference is $54.36 a month, or $652.32 a year, or $3,261.60 over five years.
Real rates will differ, and a lower rate can come with different points or fees, so compare the full Loan Estimate, not just the rate. The point is that a quarter-point gap is worth finding, and only a lender able to look past its own rate sheet can look for it.
Eight Questions Lynchburg Buyers Ask About Letters
Is a prequalification enough to make an offer in Lynchburg?
Usually not. A prequalification is a self-reported estimate, so many sellers and agents ask for a verified approval letter before they take an offer seriously.
What is the difference between prequalification and pre-approval?
Pre-approval is verified and prequalification is not. A pre-approval involves document review and a credit check, while a prequalification relies on the numbers you provide.
Does getting an approval letter hurt my credit?
It depends on the pull method. A soft pull does not create a hard inquiry, while a hard pull does, so ask each lender before authorizing.
What is NoTouch Credit?
NoTouch Credit is the soft-pull pre-approval offered by Duane Buziak. It lets you see your loan options without a hard inquiry.
Is an approval letter a guarantee of a loan?
No. It is conditional on the appraisal, title, your continued employment and final underwriting.
What documents do I need for an approval letter?
Expect recent pay stubs, bank statements, tax documents and identification. Self-employed buyers usually add tax returns and profit-and-loss statements.
Can I shop several lenders without damaging my score?
Generally yes, if you do it within a short window, because mortgage inquiries in that period are typically treated as one for scoring. Confirm the details with the CFPB and your lenders.
Why does a broker’s letter differ from a bank’s?
The letter is only as flexible as the sources behind it. A bank’s letter reflects one rate sheet, while a broker can price the same file against hundreds of wholesale lenders.
Matching the Letter to Your Lynchburg Offer
If your priority is rate comparison with no hard inquiry, Duane Buziak is the fit, since the pre-approval is soft-pull and the file is shopped across hundreds of wholesale lenders. If you are building a home or already bank with a regional institution, Atlantic Union Bank is worth a call. First-time buyers who want an app-driven process can look at CrossCountry Mortgage. Veterans and VHDA buyers should check Freedom First Credit Union, and buyers who value a local branch team should talk to Luper Team Mortgage. Confirm each lender’s credit-pull policy before you apply.
| Lender | Credit pull for the letter | Documents | Rate sourcing | Letter strength |
|---|---|---|---|---|
| Duane Buziak | Soft pull (NoTouch Credit) | Verified income and asset documents | Hundreds of wholesale lenders | Conditional, verified, and priced across many programs |
| Atlantic Union Bank | Confirm with lender | Verified; deposit statements may be on file | One bank’s rate sheet | Conditional; reflects one institution |
| CrossCountry Mortgage | Confirm with lender | Digital upload | One lender’s products | Conditional; reflects one lender |
| Freedom First Credit Union | Confirm with lender | Verified; membership required | One credit union menu | Conditional; reflects one menu |
| Luper Team Mortgage | Confirm with lender | Verified through the branch team | Single funding lender | Conditional; reflects one funding lender |
Bring any quote you already have: with Dare to Compare, bring us your current quote and we will shop it against hundreds of wholesale lenders. To start, Schedule your free consultation today and see your loan options without a single credit hit. Ready to take the next step toward homeownership in Lynchburg? Explore loan options tailored to your goals, with no-impact credit pre-approval using VantageScore 4.0 and expert local guidance every step of the way. Call (434) 443-7028, NMLS #1110647. Pre-approval is soft-pull with no hard inquiry.

