

Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
When a Lynchburg borrower’s credit report shows a recent late payment, a thin file, or a bankruptcy still working its way off the record, the instinct is often to assume no bank will touch the loan and that a hard money lender is the only path forward. Hard money financing (short-term, asset-based loans typically running 10 to 15 percent interest plus origination points) exists for a reason, but it’s rarely the cheapest reason for a homebuyer. Most borrowers in this situation actually qualify for FHA, VA, or manually underwritten conventional financing once a lender is willing to look past a single credit score cutoff. This comparison lines up Duane Buziak’s wholesale-broker model against the retail banks, credit union, and local teams active in the Lynchburg market, so you can see which structure fits a bad-credit purchase or refinance before you sign anything with double-digit interest attached.
Quick Comparison
- Lynchburg Mortgage Broker by Duane Buziak: best for borrowers already quoted hard money terms elsewhere; quote-based pricing; shops hundreds of wholesale lenders’ credit overlays instead of one institution’s cutoff.
- Freedom First Credit Union: best for existing members with VA or FHA eligibility; rates vary by membership; credit-union relationship history can factor into underwriting.
- Atlantic Union Bank: best for construction and physician-loan borrowers; bank-standard pricing; portfolios non-conforming loans in-house.
- CrossCountry Mortgage: best for first-time FHA buyers wanting hands-on guidance; retail pricing; strong local reputation for step-by-step education.
- Luper Team Mortgage: best for buyers wanting a high-volume, well-reviewed local team; priced off Fairway’s shelf; 900+ closed transactions locally.
- Loanmaven (RWM Home Loans): best for genuinely complex or previously declined credit files; priced off RWM’s shelf; 30 years of manual-underwriting experience.
1. Lynchburg Mortgage Broker by Duane Buziak
Lynchburg Mortgage Broker by Duane Buziak is an independent mortgage brokerage built specifically for borrowers who don’t fit neatly inside one lender’s box, including the credit-challenged buyers who get funneled toward hard money loans by default. Instead of running a file through a single bank’s underwriting desk and stopping there if it’s declined, Duane shops the same file across hundreds of wholesale lenders, each with its own credit overlays layered on top of FHA and VA’s baseline guidelines.
That structural difference is the whole pitch. A retail loan officer or credit union can only tell you what one shelf allows. If a borrower’s 590 score, recent late payment, or thin file doesn’t clear that one lender’s internal overlay, the file gets declined or pushed toward more expensive alternative financing. A broker with a wholesale panel can instead find the specific lender whose overlay tolerates that exact scenario, often at conventional FHA or VA pricing rather than hard money rates.
- NoTouch Credit gives you a soft-pull pre-approval using VantageScore 4.0, so you see real loan scenarios without a hard inquiry hitting your score
- FHA financing available with scores as low as 580, per HUD Handbook 4000.1, matched against the specific wholesale lenders whose overlays fit your file
- VA loans for eligible veterans and service members, with no VA-set minimum credit score and overlays that vary significantly by lender
- Access to home renovation loans and first-time buyer down payment assistance programs, useful when repair needs or limited savings compound the credit challenge
- Dare to Compare quote review, where an existing hard money or retail quote gets checked against the wholesale panel before you commit
Setup is straightforward: a soft-pull pre-approval conversation, document collection, and then Duane places the file with the wholesale lender that fits, rather than the borrower calling five different banks separately. As a newer name in the Lynchburg market, Duane doesn’t carry the decades-long local brand recognition that some established competitors on this list have built, and borrowers who want the comfort of a familiar local institution’s name on the loan may weigh that. Pricing is quote-based with no cost to get pre-approved; rate and points vary by which wholesale lender ultimately takes the file.
Best for: Borrowers who’ve been declined or quoted hard money terms elsewhere and want their file shopped across multiple lenders before accepting a rate.
2. Freedom First Credit Union
Freedom First Credit Union runs a dedicated mortgage team out of Lynchburg with a focus on VA, FHA, and VHDA loan products for members and the wider community. Courtney Woody leads much of that local lending work, and the credit union’s member-relationship model means an existing account history, direct deposit relationship, or prior loan can sometimes factor into how a file gets underwritten.
What sets Freedom First apart on this list is that member-first underwriting culture. A credit union isn’t purely rate-sheet driven the way a large bank can be; loan officers who know a member’s account history sometimes have more room to explain context around a late payment or thin file than a purely transactional retail relationship allows.
- VA, FHA, and VHDA loan specialization covers most of the government and state-backed programs a credit-challenged borrower would need
- Construction loan options are available for buyers building rather than purchasing an existing home
- Local Lynchburg branch presence means in-person appointments rather than a purely remote process
- Member-focused underwriting relationships can add context to a file beyond the raw credit score
Setup requires becoming a member first, which typically means a small share deposit and meeting Freedom First’s membership eligibility criteria before the mortgage process even begins. The loan officer manages the file day to day, similar to a retail bank experience. The real limitation is structural: Freedom First is a single-shelf institution. If its in-house underwriting declines a file or applies an overlay that doesn’t fit a particular credit situation, there’s no second lender within that same relationship to fall back on. Rates and fees vary by product; contact the credit union directly for current terms.
Best for: Existing Freedom First members with VA or FHA eligibility who want to stay within one local institution.
3. Atlantic Union Bank
Atlantic Union Bank operates a Lynchburg-based lending team led by Jay Brown, with more than 30 years of local lending experience and a particular reputation for physician loans and new construction financing. As a full-service regional bank, Atlantic Union can portfolio certain non-conforming loans in-house rather than selling them off to the secondary market immediately.
That in-house portfolio capacity is the standout feature here. It gives the bank flexibility on some file types that wouldn’t sell easily to Fannie Mae or Freddie Mac, which can occasionally help a borrower whose credit profile doesn’t fit standard conforming guidelines but who has strong compensating factors like income or reserves.
- Over three decades of local lending experience under one loan officer provides continuity through the underwriting process
- A dedicated physician and medical professional loan program addresses a specific borrower niche with unique income and debt structures
- Construction-to-permanent financing lets a borrower close once and roll from a construction loan into a permanent mortgage
- In-house portfolio loan options give the bank flexibility outside standard secondary-market guidelines for certain files
Atlantic Union runs a standard bank underwriting process, with a hard credit pull and a single rate sheet governing pricing. That’s the real limitation for a credit-challenged borrower: if the file doesn’t fit Atlantic Union’s internal overlays, there’s no wholesale panel to shop it to elsewhere within that relationship. It’s also a bank-first process, meaning appointment scheduling and paperwork move at institutional pace rather than a single loan officer’s personal bandwidth. Rates and fees are bank-standard and vary by product; contact the bank for current terms.
Best for: Borrowers building or renovating a home who want one bank managing both the construction and permanent loan.
4. CrossCountry Mortgage
CrossCountry Mortgage‘s local presence is built around loan officer April DeShano, known in the Lynchburg market for walking first-time homebuyers through the FHA process step by step. This is a retail lender relationship: one company’s products, one rate sheet, delivered with a strong emphasis on borrower education.
The distinctive value here is the hand-holding. Borrowers who’ve never bought a home, or who are nervous about how a past credit issue will be treated, often benefit from a loan officer who takes the time to explain each document request and each underwriting condition in plain language rather than assuming financial literacy the borrower doesn’t have.
- First-time homebuyer education and guidance walks new borrowers through terminology and process expectations before they feel overwhelmed
- FHA and conventional purchase loan options cover the most common paths for credit-challenged buyers
- Standard refinance options are available for existing homeowners looking to lower a rate or pull cash out
- In-person local consultations give borrowers a face-to-face relationship rather than a purely digital process
CrossCountry’s underwriting still runs off one lender’s overlays and one rate sheet, so a declined file at CrossCountry doesn’t automatically get shopped elsewhere within that same relationship. Day-to-day, the loan officer and a local processing team manage the file, and setup is a standard retail application process: consultation, document collection, and one company’s underwriting decision. Borrowers who’ve already been declined at a bank and are looking for a second opinion across multiple lenders, rather than a second retail opinion, will find CrossCountry structurally similar to the bank experience they already had. Pricing is retail lender pricing and varies by loan program; contact for a quote.
Best for: First-time buyers who want a hands-on local loan officer explaining every step of an FHA purchase.
5. Luper Team Mortgage
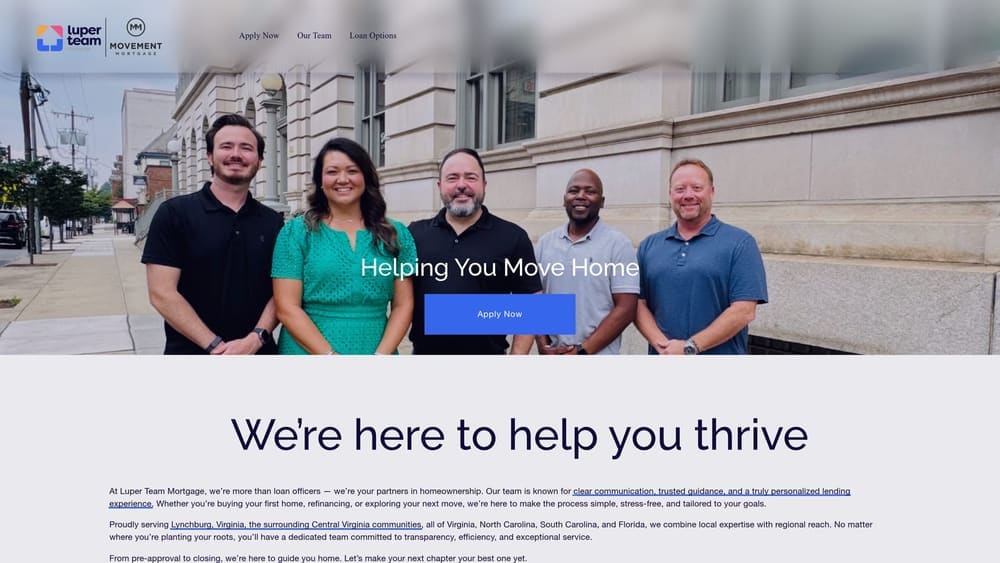
Luper Team Mortgage is a four-person local team led by Will and Joanna Luper, operating under Fairway Independent Mortgage Corporation out of a branch at 105 Hexham Dr in Lynchburg. The team has closed over 900 transactions locally and carries more than 284 online reviews, making it one of the more established names a Lynchburg borrower is likely to encounter.
Volume and reputation
That closed-loan volume and review count are the standout here: this is a team that has processed a large number of files at scale, which typically means efficient internal systems and multiple loan officers who can pick up a file if one person is out. For a borrower who wants a well-worn process rather than a boutique relationship, that scale matters.
Where the model plateaus
Every one of those loans still prices off Fairway Independent Mortgage Corporation’s own rate sheet. The team can move quickly and handle high volume, but there’s no second lender being shopped inside that same file; if Fairway’s overlay doesn’t fit a particular credit scenario, the team’s only options are Fairway’s own program variations, not an outside wholesale panel.
- 900+ closed transactions and 284+ online reviews reflect an established local track record
- FHA, VA, and down payment assistance programs are available through Fairway’s product suite
- Team-based file handling means multiple loan officers can support a single file through underwriting
- An established local branch address gives borrowers an in-person option rather than a purely remote experience
Setup follows Fairway’s standard retail process: application, document collection, and underwriting inside one company. Pricing is set by Fairway’s rate sheet and varies by program; contact the team for a quote. Borrowers who specifically want their credit file compared across multiple wholesale lenders, rather than reviewed by one high-volume team, will find this model similar in structure to the bank and retail options above it.
Best for: Buyers who want a well-reviewed, high-volume local team and don’t need their rate shopped across multiple lenders.
6. Loanmaven (RWM Home Loans)
Loanmaven is the branch led by Rhonda Holt, a lending veteran with roughly 30 years of experience, operating under RWM Home Loans (Residential Wholesale Mortgage Inc.) and carrying more than 97 Google reviews locally. Of everyone on this list besides Duane’s brokerage, this is the name most directly associated with handling complex or previously declined credit files.
The standout is depth of specific experience: three decades of manual underwriting exposure means Rhonda Holt’s team has likely seen a version of almost any credit story a Lynchburg borrower brings in, from bankruptcy timelines to non-QM alternative documentation scenarios. That pattern recognition can shorten the back-and-forth on a difficult file considerably.
- Three decades of lending experience gives the team pattern recognition across a wide range of credit-challenged scenarios
- 97+ Google reviews reflect a sustained local reputation over many years
- Manual underwriting familiarity helps borrowers whose files need a human explanation rather than an automated approval
- Awareness of non-QM and alternative documentation loan programs opens paths for self-employed or non-traditional income borrowers
Despite “wholesale” appearing in the parent company’s name (Residential Wholesale Mortgage Inc.), this is still a single-shelf retail relationship: loans price off RWM Home Loans’ own rate sheet rather than a shopped panel of competing wholesale lenders. A borrower here gets one experienced underwriter’s read on their file, not a comparison across multiple lenders’ overlays. Setup is a standard consultation and document-collection process managed directly by Rhonda Holt’s team, and pricing is set by RWM’s rate sheet, varying by program; contact for a quote.
Best for: Borrowers with a genuinely complicated credit history who want one seasoned loan officer managing the file long-term.
Matching the Right Option to Your Credit Situation
A borrower a few months past a bankruptcy discharge or foreclosure typically needs the widest possible search for a lender whose overlay has already relaxed past the FHA or VA waiting-period minimums, which argues for shopping a wholesale panel rather than accepting one bank’s answer. Veterans and eligible service members should start with VA financing before considering anything else, since VA sets no minimum credit score itself and overlays vary widely lender to lender, per VA.gov’s home loan eligibility guidance; a broker can identify which VA-approved lender’s overlay fits a specific score and file. First-time buyers who need education alongside financing may be well served starting a conversation with a retail loan officer for the hand-holding, then bringing that quote back for a wholesale comparison. Borrowers focused on renovation or new construction financing should weigh Atlantic Union’s construction-to-permanent product against Duane’s access to renovation loan programs, depending on whether portfolio flexibility or wholesale rate shopping matters more to that specific file.
| Feature | Duane Buziak / Coast2Coast | Named Competitor | Why It Matters |
|---|---|---|---|
| Number of lenders shopped per file | Hundreds of wholesale lenders | One shelf (bank, credit union, or retail company) | More lenders means more overlays checked against your specific credit profile |
| Credit check for pre-approval | Soft-pull, no-impact (NoTouch Credit, VantageScore 4.0) | Standard hard inquiry at most retail/bank lenders | Shopping options shouldn’t cost you credit score points before you’ve chosen a lender |
| Response to a declined file | File moves to a different wholesale lender’s overlay | Application typically ends or requires a new application elsewhere | One overlay’s “no” doesn’t have to be the final answer |
| Existing quote review | Dare to Compare quote check against wholesale panel | Not typically offered across competing lenders | Lets you verify whether a hard money or retail quote is actually your best option |
| Local brand tenure | New to Lynchburg market as of 2026 | Established local names (10 to 30+ years) | Established competitors offer longer local track records; Duane offers a different underwriting structure |
A worked example makes the cost gap concrete. Suppose a Lynchburg borrower needs $200,000 to purchase a property and is quoted a typical hard money structure: 12 percent annual interest, 3 points charged upfront, on a 12-month interest-only term. The 3 points alone cost $6,000 at closing (3 percent of $200,000). Interest-only payments at 12 percent annually on $200,000 run $2,000 per month, or $24,000 over the 12-month term. Total cost of that hard money loan over one year: $30,000, and the full $200,000 principal is still due as a balloon payment at the end of the term.
Compare that to an FHA loan for the same $200,000 balance, shopped across a wholesale panel at an illustrative 6.5 percent 30-year fixed rate with one origination point. The point costs $2,000 upfront. The principal-and-interest payment on a 30-year fixed amortizing loan at 6.5 percent on $200,000 is approximately $1,264 per month, or about $15,168 over 12 months, and that payment is reducing the loan balance rather than sitting interest-only with a balloon due. First-year cost: roughly $17,168 versus $30,000 for hard money, a difference of nearly $12,800 in year one alone, with no balloon payment looming and equity building instead of a full principal payoff due. Actual rates vary by borrower file and lender; this example illustrates structure, not a guaranteed quote.
Frequently Asked Questions
What credit score do I need to qualify for FHA financing instead of a hard money loan? FHA allows scores as low as 580 for maximum financing under HUD Handbook 4000.1, though individual lenders can apply stricter overlays, which is why shopping multiple lenders matters more than the published minimum.
Is there a minimum credit score for a VA loan? The VA itself sets no minimum credit score for eligible veterans and service members; each lender applies its own overlay on top of VA guidelines, so a decline at one lender doesn’t mean VA financing is off the table.
What is NoTouch Credit and how is it different from a normal pre-approval? NoTouch Credit is a soft-pull pre-approval process using VantageScore 4.0 that lets you see realistic loan scenarios without a hard inquiry hitting your credit report, which matters when you’re comparing options and don’t want each check to ding your score.
How much cheaper is FHA or VA financing than a hard money loan for the same credit situation? In a typical worked example, a $200,000 hard money loan at 12 percent interest with 3 points can cost around $30,000 in year one, versus roughly $17,000 for a comparable FHA loan at a shopped wholesale rate, a difference of nearly $13,000 with no balloon payment due.
Does a recent bankruptcy automatically disqualify me from a traditional mortgage? No; FHA and VA both allow financing after a bankruptcy discharge once a required waiting period has passed, and overlays on exactly how that waiting period is applied vary significantly by lender, which is why a declined file at one bank can still work at another.
What is manual underwriting and why does it matter for a thin credit file? Manual underwriting means a human underwriter reviews a file directly instead of relying solely on an automated approval system, which allows compensating factors like steady rent payment history or reserves to offset a thin or damaged credit file that an automated system might reject outright.
Can I get a renovation loan if my credit isn’t perfect? Renovation loan programs are generally underwritten similarly to standard FHA or conventional purchase loans, so the same overlay-shopping principle applies: a lower score doesn’t automatically disqualify a renovation loan if the right lender’s guidelines fit the file.
Is Lynchburg Mortgage Broker by Duane Buziak a legitimate local option even though it’s new to the market? Yes; Duane Buziak holds NMLS #1110647 and operates under Coast2Coast Mortgage LLC, NMLS #376205, licensed in Virginia, Florida, Tennessee, Georgia, and Washington D.C., and the wholesale-broker model is a well-established structure in mortgage lending, not a new or unproven concept.
For borrowers facing a recent bankruptcy or foreclosure, the priority is finding the lender whose overlay has already cleared the applicable waiting period, which favors shopping a wholesale panel over a single application. Veterans should lead with VA eligibility research before entertaining any other financing type, given the absence of a VA-set minimum score. First-time buyers who value education alongside financing may start with a retail conversation and then bring that quote back for comparison, while renovation and construction borrowers should weigh in-house portfolio flexibility against wholesale rate access based on their specific project. Central Virginia’s housing market has continued to see credit-distressed buyers shut out of conventional pricing unnecessarily; current regional housing statistics are tracked by Virginia REALTORS® research and statistics page.
Ready to take the next step toward homeownership in Lynchburg? Schedule your free consultation today to explore loan options tailored to your goals, with no-impact credit pre-approval using VantageScore 4.0 and expert local guidance every step of the way. Bring an existing hard money or retail quote and Duane will run Dare to Compare against hundreds of wholesale lenders to see what it should actually cost. Call (434) 443-7028; pre-approval is a soft pull with no hard inquiry to your credit.

